
Mortgage Broker Sydney · Greater Sydney
Know where you stand before you commit.
Home loans, commercial finance, SMSF, bridging and the files other brokers hand back. We work across Greater Sydney from the west, and tell you plainly what is possible before you sign
$1.5b in settled lending
MPA Top Commercial Brokers
5.0 Google rating
Phone answered 24 hours
Local, and senior only
For a standard home loan you generally do not pay us directly; the lender pays us when the loan settles. Where a scenario needs complex structuring we may charge a fee for service, explained in full before any work starts, with part of it payable only if the loan is approved.
“After selling this house we reengaged and leveraged his services to purchase our new house. Les is prompt, professional, and a pleasure to work with. He has a great understanding of the market and provides exceptional guidance throughout the process.”
Joshua Hannaford, Google review, April 2024
“Les and Mark were wonderful throughout the entire process, providing expert advice to secure the exact deal I needed for my financial goals. Communication was excellent, and they kept me informed every step of the way. My application went through smoothly with the bank and settled right on time.”
Jeff Pabon, Google review, April 2026
“Mark helped us refinance our home loan and we saved so much money on our repayments. He was super responsive and more than happy to answer all the little questions we had in a way that we could understand.”
Jessica Jamieson, Google review, December 2020


What we do
Lending help Sydney actually needs
Commercial Finance
Premises, industrial units and business lending, structured around cash flow.
Explore Commercial FinanceAsset Finance
Vehicles, fit-outs, machinery and equipment for ABN holders, sorted fast.
Explore Asset FinanceSpecialist Lending
SMSF, complex scenarios, private loan exits and the deals banks decline.
Explore Specialist LendingOn the ground across Sydney
Lending in Sydney right now
Sydney is a buyer’s market for the first time in years. Cotality’s index has the city 7.1 per cent below its February 2026 peak, with advertised stock well above average, auction clearances around half and sales volumes down more than a fifth on last year. With the cash rate at 4.35 per cent, borrowing capacity is the constraint, not stock. Vendors are negotiating, and days on market are stretching. Buyers who know their real number can use that. Buyers guessing cannot. (Figures correct as at September 2026).
Sydney lending is a set of local markets that lenders treat very differently. High-rise postcodes such as the CBD, Zetland, Mascot, Olympic Park and Parramatta carry exposure caps, minimum size rules and lower maximum LVRs. Above $2 million on the north shore or in the east, loan-size tiers, income verification and valuer conservatism tighten again. Postcodes with new-build oversupply attract shading at valuation. None of that shows on a rate comparison site. It decides what you can borrow, and from whom.
The business side is just as particular. Western Sydney is now Australia’s third-largest economy, with Western Sydney International Airport opening to passengers on 25 October 2026 and the Aerotropolis and its Metro line still under construction. Operators leasing in Wetherill Park, Smithfield, Eastern Creek and Prestons are asking whether the fund should own the unit instead. In the CBD, medical, legal and professional practices need fit-out and premises funding. Everywhere, real self-employed income sits a long way from the taxable figure a bank reads first.
We work Sydney-wide from the west: Parramatta today, Penrith from February. Penrith was one of the few Sydney regions still recording annual value growth in August 2026, and our client base runs a long way past it. The files we see weekly range from a tradie with an ATO balance to a Vaucluse owner needing out of a private loan before the rollover fee lands, an SMSF buying a strata suite, and an investor two lenders have quietly capped. The address rarely changes the answer. Knowing which credit team will read the file properly does.
Greater Sydney, read properly
The Sydney market at a glance
Median house value (Cotality, August 2026)
$1,494,878
Houses, 12-month change
−5.5%
Median unit value
$878,176
Gross rental yield
2.9% houses · 4.4% units
Rental vacancy rate (Cotality, August 2026)
2.2%
Median weekly asking rent (SQM Research, week ending 12 September 2026)
$1,131 houses · $757 units
Population
5,231,147
Median age (NSW: 39)
37
Owner-occupier share (27.8% owned outright, 33.3% with a mortgage); 35.9% rented
61.1%
Median weekly household income (NSW: $1,829)
$2,077
Largest employing industries
Hospitals 4.1% · computer system design 3.1% · banking 2.6%
Flats and apartments as a share of occupied dwellings (NSW: 21.7%)
30.7%
For property investors
Sydney gross yields sit at 2.9 per cent for houses and 4.4 per cent for units, and rents keep climbing while values fall. That favours units and higher-yield postcodes, and it puts serviceability, not purchase price, at the centre of the file. Investment property loans.
For business and industry
One in three Sydney households earns more than $3,000 a week, and professionals are the largest occupational group. Sydney business owners tend to look strong on turnover and thin on taxable income, which shapes lender appetite for premises and equipment. Commercial property finance.
For home buyers
Greater Sydney is 61 per cent owner-occupied, but 31 per cent of dwellings are apartments and that share rises every year. A Sydney house median near $1.5 million sits right at the 5 per cent deposit scheme cap, so structure decides eligibility. First home buyer loans.
Updated • ABS Census 2021 (Greater Sydney), Cotality Home Value Index (index results as at 31 August 2026, released 1 September 2026), SQM Research Weekly Rents Index (week ending 12 September 2026)
Who you'll be dealing with
Meet your Sydney brokers
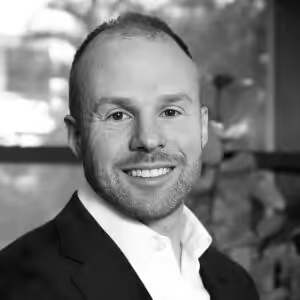
Mark Stevenson
Managing Director and Principal Broker
Managing director and principal broker, with more than 20 years in finance and over $1.5 billion settled across home, commercial, SMSF and asset lending. Mark takes the complex Sydney files: bridging, private loan exits, multi-entity self-employed income and the scenarios other brokers hand back. Clients describe him as an expert who really knows his stuff.
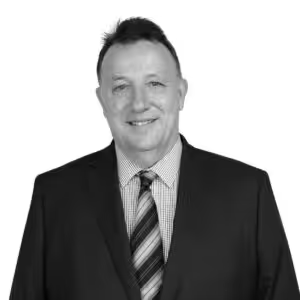
Les Patonay
Senior Mortgage Broker
Senior mortgage broker with more than twenty years in finance, handling home loans, refinances and purchases across Sydney. Clients come back to Les: one first-time buyer he helped in 2019 returned five years later for the next house, and a family he re-financed after a build went wrong still recommends him.
Serving Sydney from the city, Parramatta and Penrith
We have three offices across Sydney: the CBD, Parramatta, and Penrith. That covers the city, inner west, east and north shore from Pitt Street, the west, the Hills and the south west from Parramatta, and the outer west and Blue Mountains from Penrith. Most of our work happens by phone, video and email during business hours, because that is what suits people who are working. Face to face appointments are available at whichever office suits you. Phones are answered by a real person 24 hours a day. Distance never decides the outcome; some of our most complex Sydney settlements were for clients we met in person exactly once.
Areas we serve across Sydney:
Start with a straight answer
Call 1300 112 355
Asked by locals, answered straight
Do you only work with clients near one of your offices?
No. We have offices in the Sydney CBD, Parramatta and Penrith and we work across the whole of Greater Sydney, from the eastern suburbs and the north shore to the shire and the south west. Most files run by phone, video and email during business hours, so where you live rarely matters. Recent clients have ranged from Vaucluse to Newcastle and regional Victoria.
Will lenders finance a high-rise apartment in Sydney?
Most will, but not on the same terms. Postcodes with heavy high-rise supply, including the CBD, Zetland, Mascot, Olympic Park and Parramatta, attract exposure caps, minimum internal size rules that commonly exclude apartments under 50 square metres, and reduced maximum LVRs. Two lenders can look at the same unit and land 15 per cent apart. We check the building against policy before you offer.
I am buying above $2 million on the north shore or in the east. Does the loan size change who lends?
Yes, and it changes who lends. Above roughly $2 million, many lenders tier their maximum LVR down, apply stricter income verification and rely on more conservative valuations. Private bank and specialist lender options open up at the same time. The right structure at $3 million looks nothing like the right structure at $900,000.
Can I still use the 5 per cent deposit scheme on a Sydney house?
Possibly. The Australian Government 5 per cent deposit scheme caps Sydney purchases at $1.5 million, and the Sydney house median sits just under that. NSW stamp duty concessions stop at $1 million, so a house buyer may get one benefit and not the other. We map the scheme rules against your price point before you commit.
I am in a private loan on a Sydney property and the rollover is coming. Can you get me out?
Often, yes, and sooner than most people expect. Refinancing a private or caveat loan into a mainstream or specialist facility, or bridging until a sale completes, are ordinary Sydney files for us. What matters is timing: come to us before the rollover, not the week it lands.
Where can we meet in Sydney?
Most clients never need to. The majority of our work runs by phone, video and email during business hours. If you would rather sit down with someone, face to face appointments are available at Level 5, 115 Pitt Street in the CBD, or at our Parramatta or Penrith office.