
Caravan Finance · Asset Finance
Pre-approval before you meet the dealer, so the price and the finance stay separate.
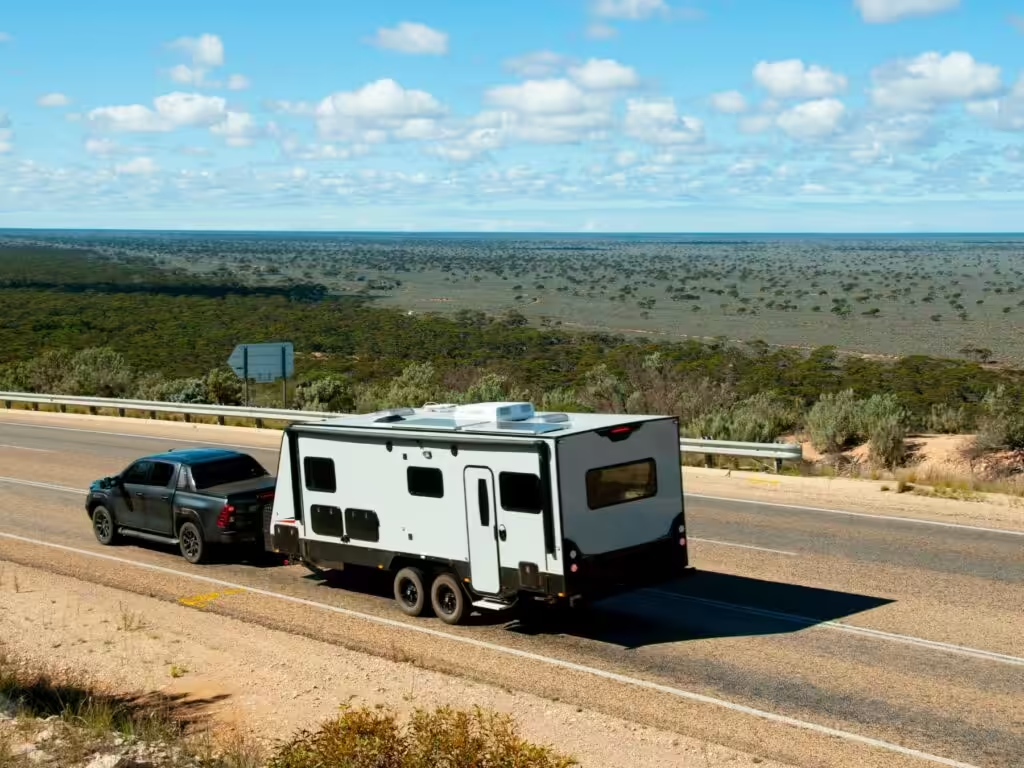
Caravan loans for new and used vans, whether you are working, self-employed or retired. We match the van and your income to the right lender and say plainly what is possible.
$1.5b in settled lending
MPA Top Commercial Brokers
5.0 Google rating
Phone answered 24 hours
What happens next
Why commercial through Evolve
Commercial is where we do our best work
Pre-approval first
Know your limit before you visit the dealer or caravan show. Pre-approval is conditional, but it lets you negotiate the price, not the repayment.
Deep lender relationships
Lenders set their own rules on van age, sellers and terms. Deep working relationships with 15 to 20 lenders mean we know who fits.
New, used or private
Dealer stock, a private sale or an older van: we find a lender whose policy fits, or tell you plainly if none will.
Dealer offer, checked
Offered finance at the dealership? We compare it with our lenders, fees and add-ons included, and tell you plainly whether it holds up.
“Les and Mark were wonderful throughout the entire process, providing expert advice to secure the exact deal I needed for my financial goals. Communication was excellent, and they kept me informed every step of the way.”
Jeff, Google review
“Evolve Lending & Finance have looked after us a number of times we have always found the team to be very friendly courteous and they just get the job done we would not go anywhere else.”
Lyn, Google review


In plain terms
Caravan finance, explained before you sign
Caravan finance is usually a secured loan, with the van itself as security, repaid over a fixed term of up to seven years. Because the van secures the loan, lenders look closely at its age, its value and who is selling it, not just your income. That is why two lenders can give very different answers on the same van.
A weekly repayment figure says nothing about the term, the fees, any lump sum left owing at the end or insurance added to the loan. We compare the whole cost across our lenders, dealer offers included. If the van is too old for a secured loan, using your equity or a personal loan may suit better. If a heavier van means a new tow vehicle, we can help you finance your next car as well.
Tell us about the van and how you earn your income. The answer will be straight: possible now, possible with changes, or not yet.
How it works
From first call to settlement
- Step
The recommendation
A 15 to 30 minute call about the van, the price and your income, then lender, repayment and total cost in writing.
- Step
Loan application
Once you agree, one application to the lender that fits, with a short document list: ID, income evidence and the van’s details when known.
- Step
Lender approval
The lender assesses you and the van, or issues a conditional pre-approval if you are still shopping. You hear the outcome and any conditions plainly.
- Step
Approval to settlement
We handle the loan documents and payment to the dealer or private seller. Pickup then depends on the seller, not the finance.
Understanding caravan loans
How caravan lending actually works
How does a caravan loan work?
A caravan loan is usually secured against the van itself and repaid in regular instalments over a set term. The lender records its interest in the van on the national register (PPSR) and removes it once the loan is paid off.
The same loans generally cover pop-tops, camper trailers, campervans and motorhomes. Older vans and private sales are where lender rules differ most, so the lender match matters more than the rate.
Should a caravan loan have a balloon payment?
Only if it suits how long you will keep the van. A balloon lowers the repayments by leaving a lump sum at the end, but it adds to the total interest and is owed whatever the van is then worth.
Some lenders only offer one on new or near-new vans. Where it fits, we set it against the van’s likely value at the end of the term, so the lump sum is one you could realistically cover.
Is home loan equity cheaper than a caravan loan?
Not always, once you count the whole cost. The home loan rate is often lower, but repaying a caravan over the rest of a mortgage can mean more interest overall, unless you clear it as quickly as a caravan loan would.
It also makes your home the security for a van that loses value each year. If you would clear it within a few years, equity can make sense, and we model both options side by side.
Can you buy a caravan through your business?
Only if the van is actually used in the business, for example as site accommodation or a mobile office. In that case a chattel mortgage in the business name may suit, and GST credits and depreciation may be claimable on the business-use share.
A van bought mainly for holidays is private use, whichever name it is bought in, so a consumer caravan loan is usually the better fit. Your accountant confirms what can be claimed, and we work alongside them.
Keep exploring
Finance the tow vehicle the same way.
When the van is too old for a secured loan.
For the boat as well as the van.
Guide · How a chattel mortgage works when a business buys the van
Know your numbers before you pick the van
Call 1300 112 355
Questions caravan buyers ask us
What types of caravans can be financed?
Finance may be available for a range of caravan and recreational vehicle purchases, including touring caravans, pop-tops, camper trailers, and some motorhomes, depending on the lender and the scenario.
Can I get finance for a used caravan?
Yes, in many cases finance may be available for used caravans. The available options will depend on the age, value, condition, and type of asset, as well as the lender’s policy.
Can I buy a caravan through a private sale?
In some cases, yes. Some lenders will consider private sale purchases, but the structure and available options can differ from dealer transactions.
What documents are usually needed for caravan finance?
Requirements vary by lender and scenario, but common documents may include identification, proof of income, liability information, and details of the caravan being purchased, including invoice or sale information where available.
Can I get pre-approval for caravan finance?
In some cases, yes. Pre-approval can help you understand your likely borrowing position before committing to a specific purchase, although final approval will still depend on the asset and lender requirements.
What affects the interest rate for caravan finance?
Pricing can vary depending on the type and age of the asset, whether the loan is secured, the purchase method, your financial position, and the lender’s policy.
Is caravan finance only for personal use?
Not always. While many caravan purchases are for personal lifestyle use, some scenarios may involve business-use considerations. The right structure will depend on how the asset is intended to be used and which lenders fit that scenario.