
Mortgage Broker Newcastle · Hunter Region
Know where you stand before you offer.
Senior brokers for Newcastle, Lake Macquarie and the Hunter, by phone or video, with our Sydney office if you want to sit down. Straight answers on rosters, contractor income and subsidence land.
$1.5b in settled lending
MPA Top Commercial Brokers
5.0 Google rating
Phone answered 24 hours
What happens next
For a standard home loan you generally do not pay us directly; the lender pays us when the loan settles. Where a scenario needs complex structuring we may charge a fee for service, explained in full before any work starts, with part of it payable only if the loan is approved.
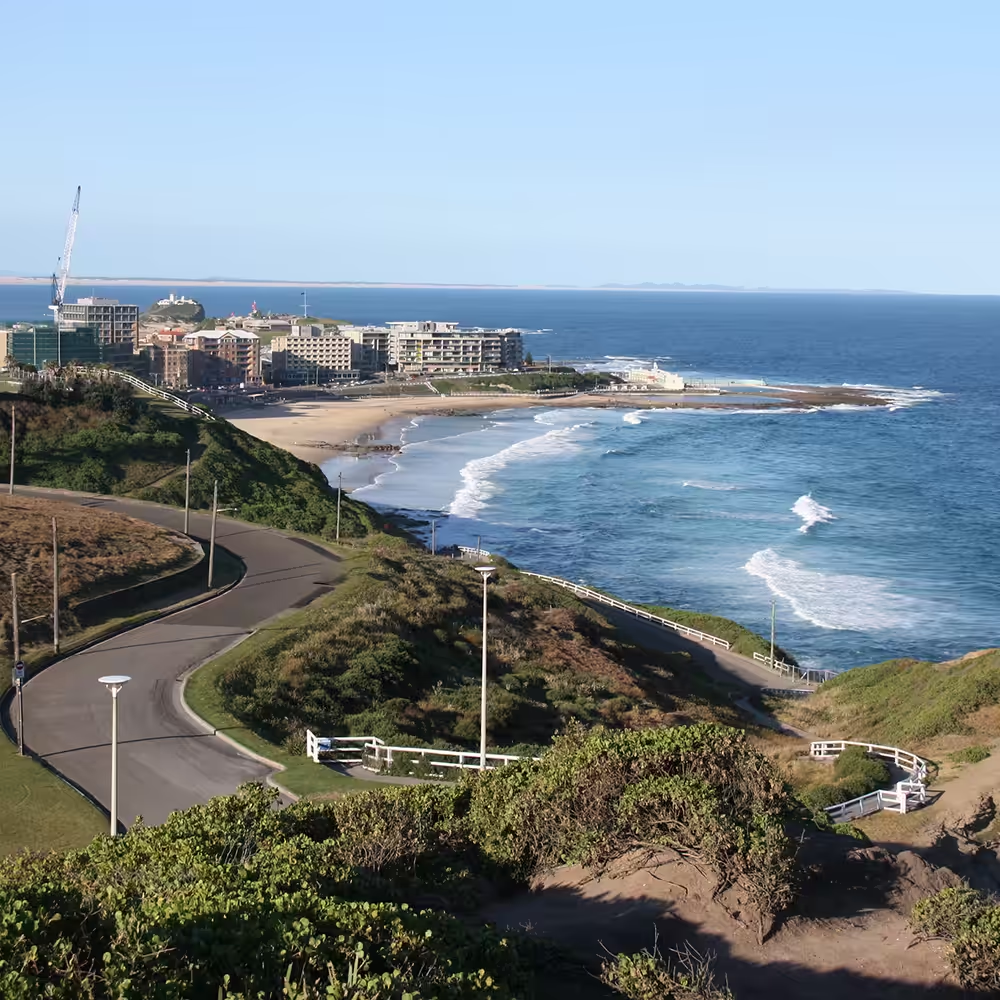
“Les and Mark were wonderful throughout the entire process, providing expert advice to secure the exact deal I needed for my financial goals. Communication was excellent, and they kept me informed every step of the way. My application went through smoothly with the bank and settled right on time.”
Jeff P, Google review, April 2026
“Mark helped us refinance our home loan and we saved so much money on our repayments. He was super responsive and more than happy to answer all the little questions we had in a way that we could understand.”
Jessica J, Google review, December 2020
“They take the time to thoroughly understand my needs and find products and a lender that matches my goals. They’re diligent, patient and prompt in following the progress of my loan.”
Evan N, Google review, March 2021


What we do
Lending help Newcastle actually needs
Home Loans
Buying, building or refinancing from Merewether to the Lake, rosters and contract income included.
Explore Home LoansCommercial Finance
Sheds, shops and premises from Carrington to Cardiff, structured around your cash flow.
Explore Commercial FinanceSpecialist Lending
SMSF purchases, complex scenarios, and files the bank declined.
Explore Specialist LendingAsset Finance
Trucks, earthmoving and trade equipment for Hunter operators and contractors.
Explore Asset FinanceOn the ground in Newcastle
What is being built, who is borrowing, and what lenders make of it
Newcastle and Lake Macquarie values peaked in April 2026 and have fallen four months in a row since. Cotality put the median dwelling at $1,019,947 at 31 August 2026, with houses down 3 per cent over the winter quarter. Sales have more than halved from the October 2025 peak, selling times have stretched from 21 days to 37, and the sharpest falls are at the top: houses above $1.2 million, Merewether beachfront and inner-city prestige apartments. For buyers that is the first real leverage in three years. For refinancers, a valuation ordered today can land under your bank’s.
The pipeline is the city’s biggest yet. DOMA’s 30-storey The Store in Newcastle West is due to complete in late 2026, with ONE and Key West beside it, and DOMA’s $1.6 billion Honeysuckle HQ, 1,000 homes in six stages on the last public land on the foreshore, has gone to State Significant Development assessment. Broadmeadow’s 313-hectare place strategy plans up to 20,000 homes and 15,000 jobs over thirty years, seeded with $14 million in the 2026-27 NSW budget. More apartments in postcode 2300 means lenders watching exposure by building, and off-the-plan buyers needing a valuation that holds at settlement.
The borrowers are not who a Sydney lender assumes. Hospitals are the region’s largest employer, and John Hunter’s new acute services building is complete and opening later in 2026. Behind that sit the university, the port, the Tomago smelter, where an August 2026 government deal secured around 1,000 jobs for a decade, and the coal mines up the valley that Newcastle suburbs commute to on rosters. Roster income arrives as base plus site allowance plus bonus, and lenders differ on how much of each they count. Contractors on ABNs and the tradespeople who will build Broadmeadow make up the rest.
Then there is the ground itself. Much of Newcastle and Lake Macquarie sits in a mine subsidence district, where Subsidence Advisory NSW approval is needed before building, extending or subdividing, and your conveyancer should confirm existing work was approved. Lenders lend on approved homes there daily; an unapproved extension is a valuation problem. The Williamtown PFAS management area is different: some lenders will not take security inside it, so check before you exchange. Add the Hunter River floodplain around Hexham and heritage terraces in Cooks Hill, and the lender that suits the property matters as much as the rate.
The numbers behind the market
Median house value, Newcastle and Lake Macquarie (Cotality, 31 August 2026)
$1,059,758
House values, three months to 31 August 2026 (Cotality)
-3.0%
Median unit value, Newcastle and Lake Macquarie (Cotality, 31 August 2026)
$808,899
Gross rental yield, Hunter Region (SQM Research, 15 September 2026)
3.6% houses · 4.3% units
Rental vacancy rate, Hunter Region (SQM Research, August 2026)
1.2%
Median weekly asking rent, Hunter Region (SQM Research, week ending 20 September 2026)
$679 houses · $590 units
Residents of Newcastle and Lake Macquarie (2021)
390,519
Median age (NSW: 39)
40
Households that own their home outright or with a mortgage
67.8%
Median weekly household income (NSW: $1,829)
$1,676
Largest employing industries
Hospitals, social assistance, aged care
Dwelling mix; new towers in Newcastle West are changing the 2300 postcode faster than the region
78.2% houses · 8.7% apartments
Property investors
House values are off 3 per cent in a quarter and selling times have nearly doubled since April, so buyers have leverage they did not have a year ago. With 29 per cent of households renting and hospitals the largest employer, tenant demand is steady. Structure matters more than rate. SMSF loans
Business and industry
Hospitals, the university, the port and a smelter now secured for a decade give Newcastle a payroll that lenders trust. If you lease in Carrington, Cardiff or Beresfield and the rent review is due, buying your premises is a cash-flow question we can answer with the actual numbers. commercial property loans
Home buyers
Two-thirds of households already own, and a median house above $1 million against a median income of $1,676 a week means most first buyers here need a guarantor, a scheme place or a roster income counted properly. That is a lender-selection job, and it starts before you inspect. guarantor home loans
Updated • Cotality Home Value Index (31 August 2026, Newcastle and Lake Macquarie SA4), Cotality Regional Market Update, SQM Research Weekly Rents Index and Vacancy Rates, Newcastle, ABS Census 2021 QuickStats (Newcastle and Lake Macquarie SA4; New South Wales)
Who you'll be dealing with
Meet your Newcastle brokers
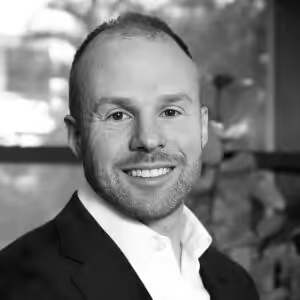
Mark Stevenson
Managing Director and Principal Broker
More than twenty years in lending and over $1.5 billion settled across home, commercial, SMSF and development loans. Clients describe him as an expert who knows his stuff and stays focused on their situation, and he takes every Newcastle file with roster income, a subsidence-district block or a declined application himself.
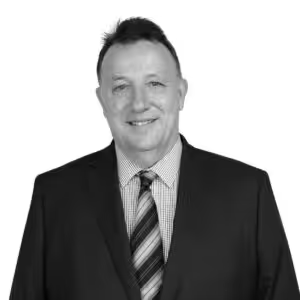
Les Patonay
Senior Mortgage Broker
Senior Mortgage Broker who has looked after clients through first homes, sales and second purchases for over twenty years. Clients describe him as prompt, professional and a pleasure to work with, with a strong understanding of the market and the patience to answer every question in full.
Serving Newcastle and the Hunter from Sydney
We do not have a Newcastle office, and we would rather say so than pretend. Our home office for Newcastle and Hunter files is Sydney CBD, at Level 5, 115 Pitt Street, Sydney NSW 2000, a short walk from Central if you come by train. If Parramatta (153 Macquarie Street, Suite 20 Level 14/3 Parramatta Square, Parramatta NSW 2150) or Penrith (Unit 2D/21 Lawson Street, Penrith NSW 2750) is more convenient, we can meet you there. Most Hunter clients never visit any office: the whole file runs by phone, video and electronic signing. Three ways of working: by phone or video first; face to face at our Sydney office; and phones answered by a real person, 24 hours a day.
Nearby areas we serve:
Start with a straight answer
Call 1300 112 355
Asked by locals, answered straight
Do you have an office in Newcastle?
No, and we will not pretend otherwise. Newcastle and Hunter files run by phone, video and electronic signing from first call to settlement. If you want to sit down with your broker, our nearest office is Sydney CBD at Level 5, 115 Pitt Street, a short walk from Central; Parramatta and Penrith are also available.
Will lenders count my mining roster allowances and bonuses?
Usually some, rarely all. Base salary counts in full. Regular site and shift allowances shown on payslips are counted in full by some lenders and at 80 per cent by others. Bonuses generally need two years of history; casual roster work often needs six to twelve months in the role. The lender chosen can move your borrowing capacity by tens of thousands.
My block is in a mine subsidence district. Does that affect the loan?
Not by itself. Lenders take approved homes in the Newcastle and Lake Macquarie districts every day. What matters is that anything built, extended or subdivided had Subsidence Advisory NSW approval, because a valuer who finds unapproved work will note it and the lender may discount or decline. Have your conveyancer confirm approvals and past claims before you exchange.
Can I get a loan on a property in the Williamtown PFAS area?
It depends on the lender, and the list is short. Some will not take security inside the Williamtown Management Area at all; others will at a lower loan-to-value ratio with a valuation that addresses the contamination. Give us the address before you offer and we will confirm which lenders will look at it.
Are lenders still funding new apartments in Newcastle West and Honeysuckle?
Yes, with conditions. Most lenders cap how much of any one building they will hold, ask for a larger deposit on smaller units, and value off-the-plan purchases at settlement, not at contract. After four months of falling values, that valuation gap is the risk to plan for. We check the building and the lender’s exposure before you sign.
What deposit do I need to buy a first home in Newcastle at today's prices?
With the median house above $1 million, a 20 per cent deposit is around $210,000 plus costs, so most first buyers here use a smaller deposit with lenders mortgage insurance, a family guarantee, or the federal 5 per cent deposit scheme, whose price cap covers most of Newcastle. NSW stamp duty relief also applies below its thresholds. We work out which combination fits.