
Mortgage Broker Perth · Western Australia
Know what's possible before you sign.
Home loans on FIFO and self-employed income, SMSF, commercial and the files other brokers hand back. We work with Perth clients by phone and video, and tell you plainly what’s possible.
$1.5b in settled lending
MPA Top Commercial Brokers
5.0 Google rating
Phone answered 24 hours
What happens next
For a standard home loan you generally do not pay us directly; the lender pays us when the loan settles. Where a scenario needs complex structuring we may charge a fee for service, explained in full before any work starts, with part of it payable only if the loan is approved.
“Friendly and highly professional service. Looked at a range of options to suit us and followed up on changes quickly and efficiently. Very happy with the finance secured.”
Christine S, Google review (February 2025)
“Les and Mark were wonderful throughout the entire process, providing expert advice to secure the exact deal I needed for my financial goals. Communication was excellent, and they kept me informed every step of the way. My application went through smoothly with the bank and settled right on time.”
Jeff P, Google review (April 2026)
“They take the time to thoroughly understand my needs and find products and a lender that matches my goals. They’re diligent, patient and prompt in following the progress of my loan.”
Evan N, Google review (March 2021)


What we do
Lending help Perth actually needs
Commercial Finance
Kewdale, Canning Vale or Henderson premises, and lending built on cash flow.
Explore Commercial FinanceAsset Finance
Trucks, earthmoving and mining services equipment for WA ABN holders, sorted fast.
Explore Asset FinanceSpecialist Lending
SMSF, complex scenarios, private loan exits and the deals WA banks decline.
Explore Specialist LendingOn the ground in Perth, from a distance
Lending in Perth right now
Perth has just come off the strongest run of any capital. Dwelling values rose 79.7 per cent in five years and the median touched $1 million before peaking in April 2026. Since then the market has turned: values are 3.2 per cent off the peak, listings passed 7,000 in August for the first time since early 2023, and nearly half of July’s sales went for under the asking price. Three cash rate rises this year and the May Budget’s negative gearing changes did most of that. For a borrower, it means checking the valuation before the offer, not after.
The other thing a lender sees on a Perth file is the income. Iron ore mining employs 2.6 per cent of Greater Perth’s workforce, six times the national share, and much of it is FIFO: swing rosters, site allowances, casual or labour hire contracts. Lenders treat all of it differently. Some count allowances in full, some shade them, some ignore them, and casual income can need anything from six months of history to two years. Regional security is similar: Pilbara and Goldfields postcodes carry lower maximum LVRs with many lenders, and a few will not lend there at all.
WA business runs on contractors: mining services operators in Welshpool and Kewdale, transport and civil crews in Hazelmere and Forrestdale, fabricators around Kwinana and Henderson, where Defence confirmed the AUKUS submarine sustainment site in August 2026. Their income is lumpy, tied to contract cycles and shutdown seasons, and a tax return rarely shows the real picture. Add a labour market where construction and mining compete for tradespeople, and fixed price building contracts signed two years ago, and you get builders under pressure and construction loans timed around delays. Equipment finance, premises and ATO arrangements are weekly conversations.
Growth corridors tell the rest. Serpentine-Jarrahdale, Mandurah, Rockingham and Armadale led Greater Perth this year, all house and land. WA widened its first home owner duty concessions from 7 May 2026: no duty up to $600,000 and a concessional rate to $800,000. The $10,000 grant applies to new homes up to $800,000, and the federal 5 per cent deposit guarantee caps Perth purchases at $850,000. With the median above all three, matching buyer, scheme and build contract is most of the job. We do that for Perth clients from Sydney, by phone and video; distance has never decided an outcome.
Greater Perth, read properly
The Perth market at a glance
Median house value, Greater Perth
$1,043,478
Houses, 12-month change
+15.6%
Median unit value, Greater Perth
$733,223
Gross rental yield
3.8% houses · 5.0% units
Rental vacancy rate (SQM Research, July 2026)
0.6%
Median weekly rent (REIWA, August 2026)
$750 houses · $700 units
Population
2,116,647
Median age (Australia: 38)
37
Owner-occupied (41.9% with a mortgage, 28.5% owned outright)
70.4%
Median weekly household income (Australia: $1,746)
$1,865
Largest employing industries
Hospitals 4.4% · Iron ore mining 2.6% · Primary education 2.5%
Separate houses as a share of dwellings (flats and apartments: 7.6%)
77.8%
For property investors
Perth houses gross 3.8 per cent and units 5.0, on a 0.6 per cent vacancy rate, the tightest mainland capital after Darwin. Values are 3.2 per cent off the April peak. The question is which lender will value the property where you paid. Investment property loans.
For business and industry
Iron ore mining employs 2.6 per cent of the workforce here against 0.4 per cent nationally, and one in five workers logs 45 hours or more. Contractors, subcontractors and mining services businesses carry income that lenders routinely misread. Structure decides the outcome. Commercial property loans.
For home buyers
Seven in ten Greater Perth homes are owner-occupied and 78 per cent are separate houses, so most first purchases here are house and land. WA’s duty concessions, the $10,000 grant and the 5 per cent deposit guarantee each carry a different price cap. First home buyer loans.
Updated • ABS Census 2021 (Greater Perth), Cotality Home Value Index (index results as at 31 August 2026, released 1 September 2026), SQM Research National Vacancy Rates (July 2026, released 13 August 2026), REIWA Perth market update (August 2026, released 6 September 2026)
Who you'll be dealing with
Meet the brokers who handle Perth lending
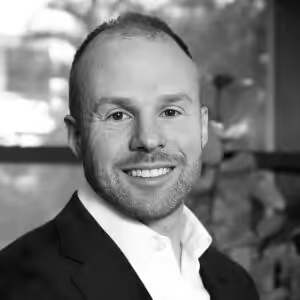
Mark Stevenson
Managing Director and Finance Broker
More than twenty years in lending and over $1.5 billion settled across home, commercial, SMSF and asset finance, including bridging, private loan exits and entity structures most brokers never see. Named in client reviews for being responsive and explaining things in plain terms. Handles the complex end of every Perth file.
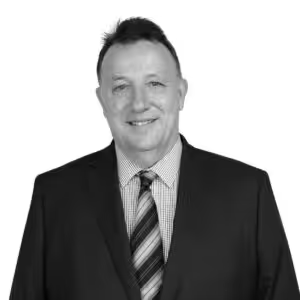
Les Patonay
Senior Mortgage Broker
More than twenty years in finance. First homes, refinances and clients who come back for a second and third property; named in the most recent Evolve-branded review on file for a loan that settled on time.
Serving Perth from Sydney, by phone and video
We serve Perth from our Sydney CBD office at Level 5, 115 Pitt Street, Sydney NSW 2000. Our Parramatta office, 153 Macquarie Street, Suite 20 Level 14/3 Parramatta Square, and our Penrith office, Unit 2D/21 Lawson Street, if either is ever more convenient. Clients nowhere near an office, which is every Perth client, work with us the way most clients do: by phone, video and email in business hours, scheduled in Perth time, with documents signed electronically. Three ways of working: by phone or video, how most of our clients do it; face to face appointments at our Sydney CBD office if you are in town; and phones answered by a real person 24 hours a day.
Other areas we serve:
Start with a straight answer
Call 1300 112 355
Asked by locals, answered straight
Can a Sydney-based broker arrange a home loan in Perth?
Yes. Credit licensing under the NCCP Act is national, lenders are national and WA settlements run electronically. We work with Perth clients by phone, video and email, scheduled in Perth time. If you are ever in Sydney, face to face appointments are available at our Sydney CBD office, Level 5, 115 Pitt Street.
How do lenders treat FIFO and mining income?
Very differently, which is why the lender is chosen before you apply. Base salary is always counted. Site allowances and roster loadings are counted in full by some lenders, shaded by others and ignored by a few. Casual and labour hire income needs a track record of varying length. A decline on FIFO income usually means the wrong lender saw it first.
Can I borrow against a property in Karratha, Port Hedland or Kalgoorlie?
Usually, with fewer lenders and a lower maximum LVR than the same purchase in Perth. Most lenders put regional and mining postcodes into categories that cap lending, and some exclude particular towns. SMSF and commercial lending in these postcodes is tighter again. We check the postcode against policy before you make an offer.
What help is there for first home buyers in Western Australia right now?
Three things, each with its own cap. Since 7 May 2026, first home buyers pay no transfer duty on homes up to $600,000, with a concessional rate to $800,000. The $10,000 First Home Owner Grant applies to new homes only, capped at $800,000. The federal 5 per cent deposit guarantee removes lenders mortgage insurance, capped at $850,000 in Perth. Duty still applies above the state thresholds even when the federal guarantee is used.
My Perth valuation came in under the contract price. What now?
Common now the market has come off its peak, and usually fixable. Options include a valuation through a different lender, a lender whose panel valuer reads the suburb differently, restructuring the deposit, or bringing in equity or a guarantee. Come to us the day the number lands, not the week before settlement.